If your GSTR-2B and your purchase register do not agree, the gap is usually a small list of repeatable causes: a missing supplier filing, a wrong GSTIN, a timing difference or a data-entry slip. This guide shows a step-by-step GSTR-2B mismatch reconciliation you can finish before you file GSTR-3B, so that you claim only the input tax credit (ITC) you are entitled to.
What GSTR-2B is and why it must match your books
GSTR-2B is an auto-drafted, read-only statement of ITC available to you for a month. It is built from the returns your suppliers file (GSTR-1, GSTR-5 and similar) and from other documents such as import data. Once generated for a month, it does not change, which makes it a stable base for comparison. The GST portal generates it on the 12th day of the succeeding month.
Your purchase register is the other side: every purchase invoice, debit note and credit note you have recorded in your books. Under Section 16(2)(aa) of the CGST Act, ITC is generally allowed only when the supplier's details appear in your GSTR-2B. If an invoice is in your books but not in GSTR-2B, claiming that credit is risky. If it is in GSTR-2B but not in your books, you may be missing a purchase, or the invoice may not be yours at all.
Step 1: Download both sides for the same period
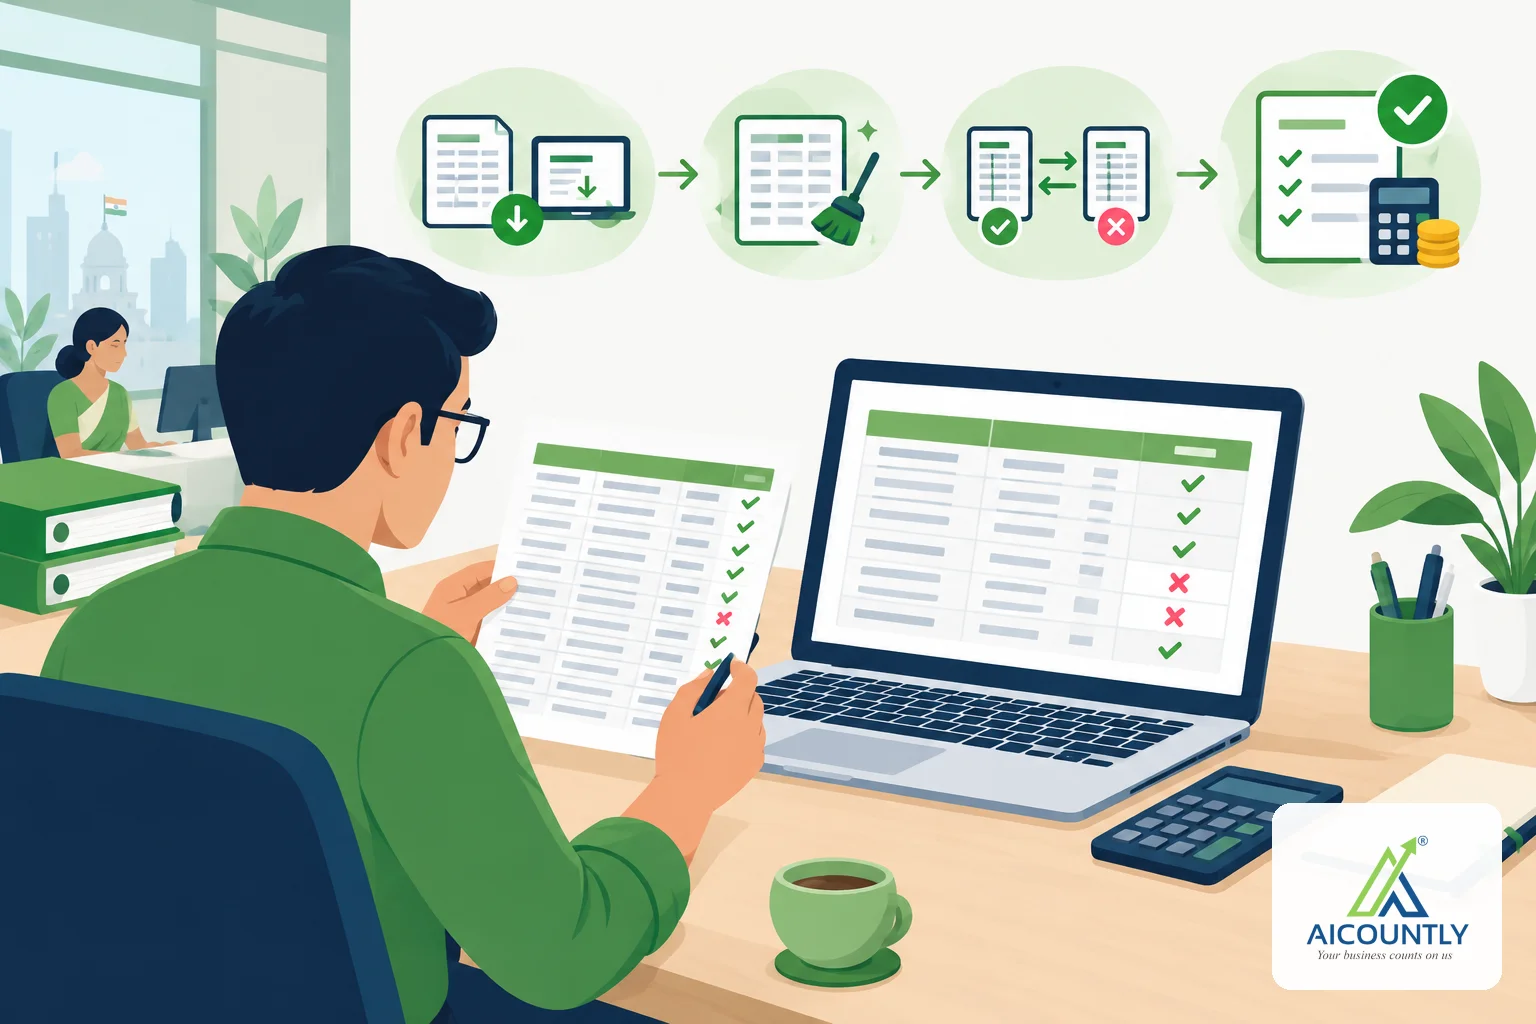
Download GSTR-2B for the month from the GST portal (the Excel version is easiest to work with), and export your purchase register for the same month. Include debit notes and credit notes. Keep the invoice date, invoice number, supplier GSTIN, taxable value and each tax head (IGST, CGST, SGST) in separate columns.
Step 2: Clean the data before you compare
Most "mismatches" are formatting problems rather than real differences. Before matching, fix these:
- Remove spaces, slashes and leading zeros in invoice numbers where the supplier has entered them differently.
- Make sure every GSTIN has 15 characters and matches the supplier master.
- Use one date format and compare by tax period, not by the date you received the bill.
- Separate B2B invoices, import entries, and reverse charge purchases, since they sit in different parts of GSTR-2B.
Step 3: GSTR-2B mismatch reconciliation, invoice by invoice
Match on supplier GSTIN plus invoice number first, then compare the amounts. A simple spreadsheet lookup works for small volumes. Sort every line into one of four buckets:
BucketMeaningUsual action MatchedSame invoice and amounts on both sidesClaim the ITC Amount differsInvoice found, values differCheck the original invoice, then correct your books or ask the supplier to amend In books, not in GSTR-2BSupplier has not filed or reported itHold the credit and follow up In GSTR-2B, not in booksPurchase not recorded, or not yoursVerify, then record it or ignore itStep 4: Understand the common causes of mismatch
Once the buckets are ready, look for patterns rather than chasing every line.
- Supplier filed late or not at all. The invoice will show in a later month's GSTR-2B, or never.
- Wrong GSTIN on the invoice. The credit shows against another business.
- Invoice number or date typed differently. Common with long alphanumeric numbers.
- Credit notes and debit notes. A credit note may be reported by the supplier in a different month from the one in which you recorded it.
- Blocked credit. Some purchases appear in GSTR-2B but are not eligible under Section 17(5); read our guide on blocked credit under Section 17(5).
- Reverse charge. Tax you pay under RCM is not a supplier-filed ITC line in the same way; see how to account for, pay and claim ITC on RCM.
Step 5: Decide what ITC to claim in GSTR-3B
Claim ITC for the matched invoices and for eligible items in GSTR-2B. For invoices missing from GSTR-2B, hold the credit until the supplier reports them. Invoices that stay unpaid to the supplier can also trigger a reversal; read about the 180-day rule for unpaid supplier invoices. Also remember that there is a time limit for claiming ITC under Section 16(4); our note on the Section 16(4) ITC time limit explains how to track it.
Step 6: Chase suppliers with a short, specific message
For each missing invoice, send the supplier a message with the invoice number, date, taxable value and tax amount, and ask which GSTR-1 period it will be reported in. Keep a log of who you contacted and when. A supplier who regularly files late is a risk to your cash flow, so consider adjusting payment terms.
Step 7: Make it a monthly habit
- Record purchases in your books throughout the month, not at filing time.
- Once GSTR-2B is available, run the comparison above.
- Resolve what you can, and park the rest in a "pending from supplier" list.
- File GSTR-3B using the reconciled figures. Our GSTR-3B pre-filing checklist and the GSTR-1 vs GSTR-3B reconciliation checklist pair well with this routine.
- Carry the pending list into next month's review.
Key takeaways
- GSTR-2B is a fixed monthly statement; compare it with your purchase register for the same period.
- Clean invoice numbers, GSTINs and dates before matching to remove false mismatches.
- Sort every line into matched, amount differs, missing in GSTR-2B or missing in books.
- Do not claim ITC for invoices that are not in GSTR-2B; follow up with the supplier instead.
- Reconcile every month, before GSTR-3B, so differences never pile up.
Good reconciliation starts with clean purchase entries in your books. Keeping purchases recorded as they happen, with supplier GSTIN and invoice details, makes this monthly check much faster, and this is the kind of day-to-day bookkeeping discipline that accounting software such as Aicountly Smart Books is meant to support. This is general guidance; confirm specifics for your business with your chartered accountant.