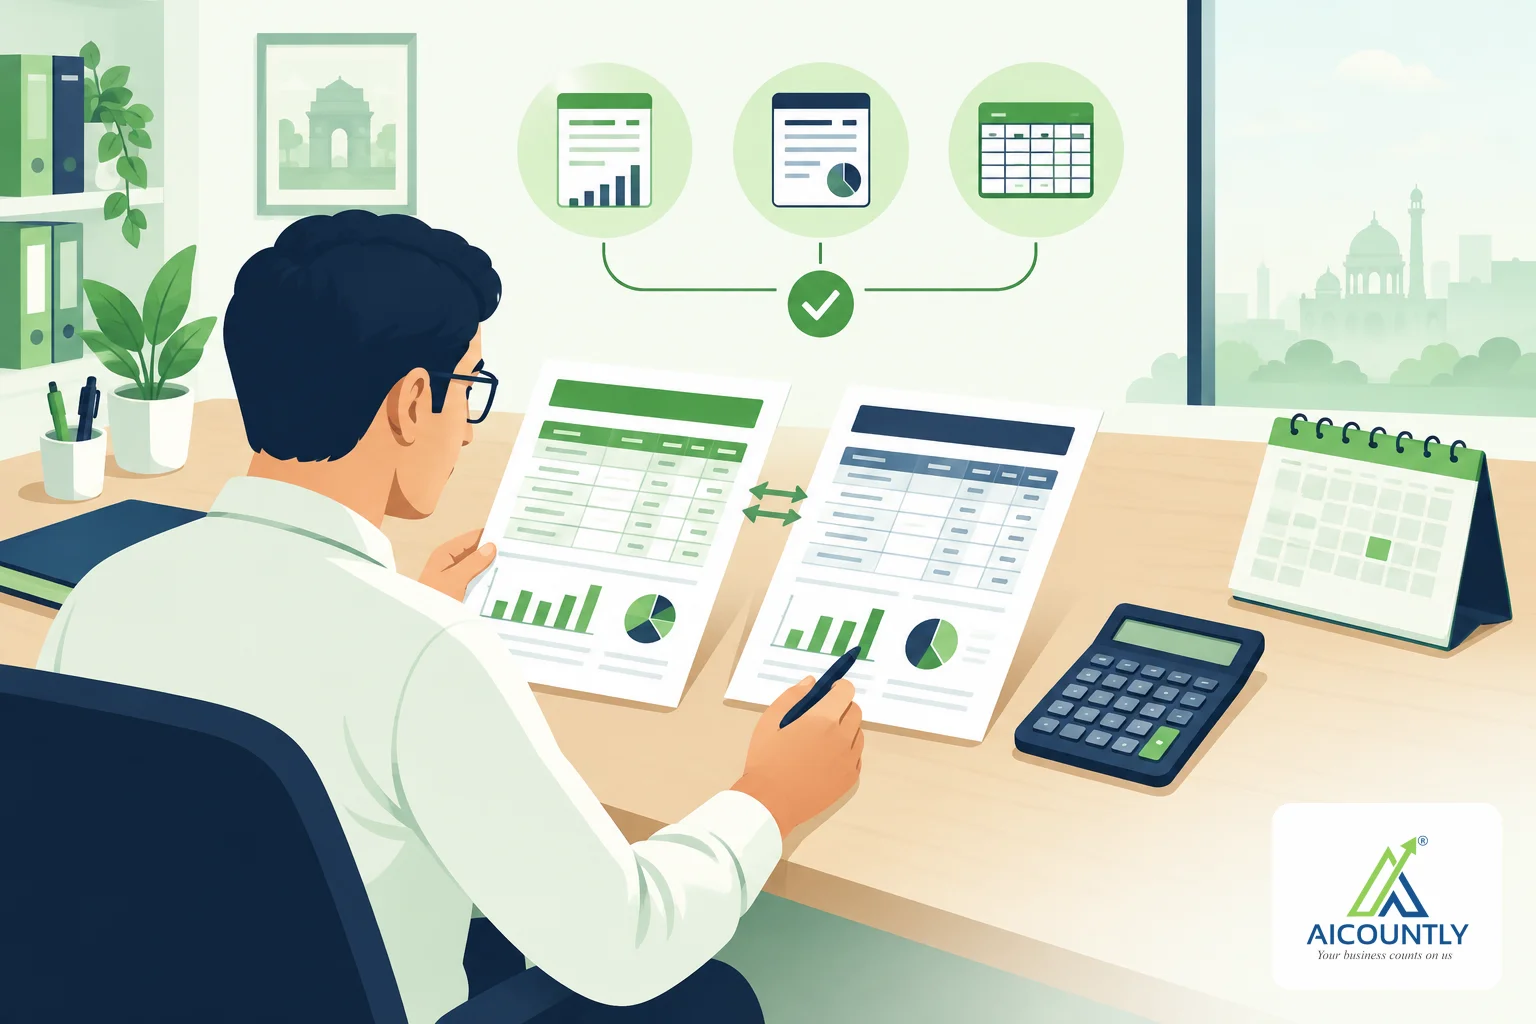
If your GSTR-1 shows one figure for sales and your GSTR-3B shows another, the GST system and your tax officer will both notice. The fix is a simple monthly GSTR-1 vs GSTR-3B reconciliation: compare the two returns, explain every difference, and correct it before the next due date.
This guide walks you through why the two returns differ, how to compare them in about thirty minutes, and what to do when the numbers do not match.
Why GSTR-1 vs GSTR-3B reconciliation matters every month
GSTR-1 is the statement of your outward supplies: invoice-wise details of what you sold, to whom, and at what tax rate. GSTR-3B is the summary return in which you declare the tax liability, claim input tax credit (ITC) and pay the tax. Both describe the same month of sales, so the tax liability on sales in GSTR-3B should normally agree with the tax shown in GSTR-1.
Differences are not always errors. Timing, amendments and credit notes can legitimately create gaps. The aim of reconciliation is to know the reason for every gap, not to force the totals to match.
Common reasons the two returns differ
- Invoices missed in one return. A sale was entered in your books and filed in GSTR-3B, but the invoice was never uploaded to GSTR-1, or the other way round.
- Credit and debit notes. A credit note issued in the month reduces your liability, but it may be reported in a different period from the original invoice.
- Amendments. Corrections to earlier invoices appear in a later GSTR-1, so the current month can show amounts that belong to an older sale.
- Advances received. Tax on advances may be reported in one place before the final invoice is raised. Check how your own entries treat them.
- Rate or place-of-supply errors. The invoice total agrees, but the split between IGST and CGST/SGST does not.
- Reverse charge and exempt or nil-rated supplies. These sit in separate tables, so a plain total-to-total comparison can mislead.
Step 1: Gather three documents
Before you start, keep these ready for the same tax period:
- The filed or draft GSTR-1 summary.
- The GSTR-3B summary of outward supplies and tax payable.
- Your sales register from your books, with credit notes and debit notes shown separately.
The sales register is your anchor. If both returns disagree with it, the problem is in your books. If only one disagrees, the problem is in that return.
Step 2: Compare taxable value and tax, head by head
Make a small table with one row each for taxable value, IGST, CGST, SGST/UTGST and cess. Fill in three columns: sales register, GSTR-1 and GSTR-3B. Then compute the difference between each pair.
HeadSales registerGSTR-1GSTR-3BDifference to explain Taxable valueYour figureYour figureYour figureRegister vs return, return vs return IGSTYour figureYour figureYour figureLook at inter-state invoices CGST and SGSTYour figureYour figureYour figureLook at intra-state invoices CessYour figureYour figureYour figureOnly if applicableWork head by head rather than on the grand total. A shortfall in IGST can be hidden by an excess in CGST, and the total alone will look fine.
Step 3: Trace each difference to an invoice
For every difference, find the invoice or note that causes it. A practical order is:
- List invoices present in the sales register but missing from GSTR-1.
- List invoices in GSTR-1 that are not in the register, which usually means a duplicate or a wrong date.
- Check credit notes and debit notes for the month and the period in which each was reported.
- Check the rate and the place of supply on the invoices that remain.
Write one line of explanation against each item. This note becomes your working paper if a notice ever arrives.
Step 4: Decide how to correct it
What you do depends on whether the return is already filed.
- Before filing: correct the entry in your books or the draft return and compare again.
- After filing GSTR-1: use the amendment facility available on the GST portal in a later period, and check the portal for the current method of correcting a filed return.
- After filing GSTR-3B: an under-reported liability is generally cleared with the next return along with interest on the late tax. Interest on delayed payment of tax is charged under Section 50 of the CGST Act, so do not leave a known shortfall for months.
Procedures on the portal change from time to time, so check the current GST portal guidance or ask your chartered accountant before you correct a filed return.
Make it a monthly habit
The easiest reconciliation is the one you do every month before you file. Set a fixed day just before the GSTR-1 date, match the sales register to the draft GSTR-1, and only then prepare GSTR-3B. Keep the comparison sheet with your month-end records.
For the dates that matter this cycle, see our November 2026 compliance calendar, the GSTR-1 filing checklist for October 2026 and the worked example on late fee and interest on GSTR-3B. If credit notes are a regular cause of differences in your business, read about GST credit notes under Section 34.
Key takeaways
- Compare the sales register, GSTR-1 and GSTR-3B for the same period, head by head.
- Not every difference is an error; amendments, credit notes and timing explain many gaps.
- Trace each difference to an invoice and write a one-line reason.
- Fix known shortfalls promptly, because interest runs on late tax.
- Do the check every month before filing, not after a notice.
If you want your sales records and books in one place to make this monthly check easier, you can explore Smart Books from AICOUNTLY. This article is general guidance, so please confirm the treatment of specific transactions with your chartered accountant.