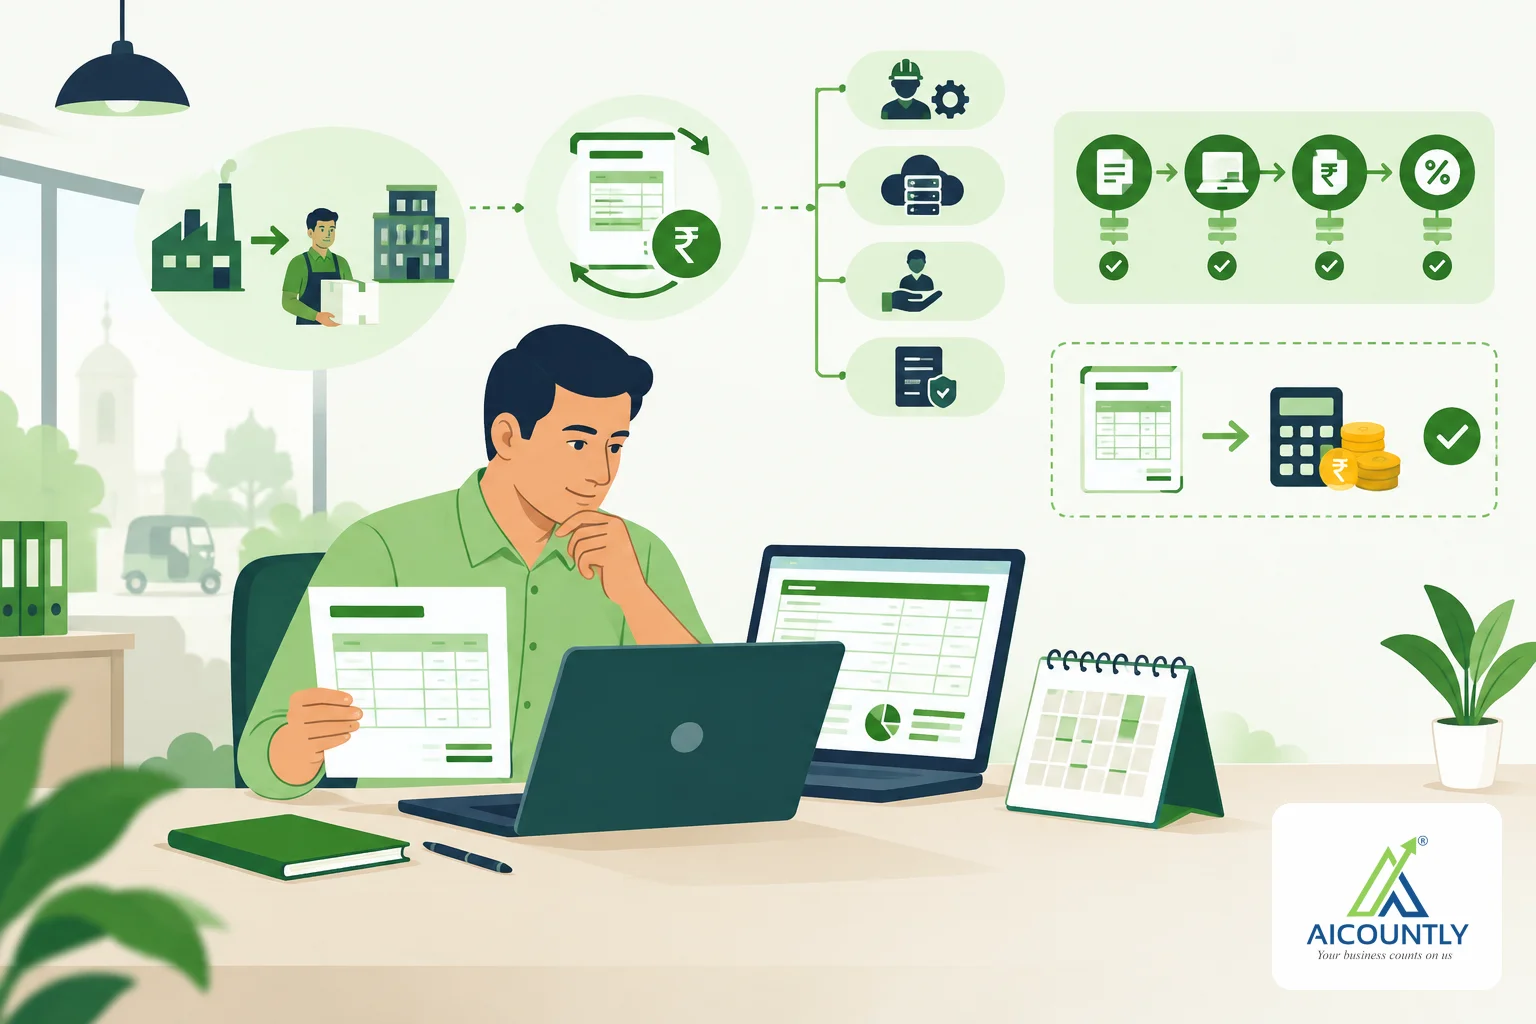
Reverse charge under GST means you, the buyer, pay the tax to the government instead of your supplier. If your business receives certain services or goods covered by reverse charge and you ignore it, you can end up with unpaid tax, interest and blocked input tax credit. This guide explains how the GST reverse charge mechanism (RCM) works, how to account for it step by step, and where small businesses usually go wrong.
What is the GST reverse charge mechanism?
Normally the supplier collects GST from you and deposits it. Under reverse charge, the law shifts the liability to the recipient. The main provisions are Section 9(3) and Section 9(4) of the CGST Act, and the equivalent provisions of the IGST Act for imports of services (Section 5(3) and 5(4)).
The government notifies which supplies fall under RCM. The list changes from time to time, so always check the latest CBIC notification or the GST portal before you rely on any list, including ours.
Common supplies where RCM may apply
Small businesses most often meet reverse charge in these situations. Confirm the current notification and conditions for each one.
- Goods transport agency (GTA) services: when you pay a transporter who issues a consignment note, the recipient may have to pay GST under RCM, depending on the option the transporter has chosen.
- Legal services: services from an advocate or firm of advocates to a business entity are a long-standing RCM category.
- Import of services: if you buy a service from a supplier located outside India, IGST is generally payable by you under reverse charge.
- Specified supplies from unregistered suppliers: only certain notified goods or services bought from unregistered persons attract RCM. It is not a blanket rule for every purchase from an unregistered vendor.
How to account for reverse charge: step by step
- Identify the supply. Check whether the purchase is in the notified RCM list and whether the supplier is registered.
- Raise a self-invoice where required. When you buy from an unregistered supplier on RCM, you issue the invoice to yourself. Keep it with the purchase record.
- Work out the time of supply. This decides the month in which you owe the tax. It depends on the date of receipt, payment and invoice, so read the rule for goods and services separately.
- Report it in GSTR-3B. Show the inward supplies liable to reverse charge in the section meant for them, and add the tax to your liability.
- Pay in cash. Tax under RCM is paid through the electronic cash ledger. It cannot be paid by using your input tax credit balance.
- Claim input tax credit. After you have paid, you can claim ITC on the RCM tax, subject to the usual conditions: the supply is for business use, it is not a blocked credit, and the time limit is met.
A simple worked example
Suppose your firm pays a transporter Rs 10,000 for moving goods, and the supply is covered by RCM at 5% GST. The RCM tax is Rs 500. You report Rs 500 as tax payable on reverse charge in your GSTR-3B for the month of the time of supply and pay it from your cash ledger. In the same or a later return, you claim Rs 500 as ITC, if you are eligible. The net cash effect over time is usually timing, but the cash must go out first. Note that the rate and conditions depend on the transporter's option and the current notification, so treat the figures as illustrative.
Common mistakes to avoid
- Assuming every purchase from an unregistered supplier is under RCM.
- Trying to discharge RCM liability from the ITC ledger instead of cash.
- Claiming ITC before actually paying the RCM tax.
- Forgetting the self-invoice, which weakens your records during a notice or audit.
- Ignoring RCM on imported services such as software subscriptions or overseas consulting.
- Missing the ITC time limit; see our guide on the Section 16(4) deadline.
Why small businesses should care about RCM
RCM is easy to miss because no tax appears on the supplier's bill. The liability still exists in your books. Many notices arise when a business pays a transporter, an advocate or an overseas vendor and never records the reverse charge tax. Because the tax is paid in cash first and recovered as credit later, it also affects your working capital in the month it falls due. Build a short monthly habit: scan your purchase register for these supplier types before you prepare GSTR-3B, mark the RCM entries, and compute the tax together with the time of supply. Share the list with your accountant so that nothing depends on memory.
Keep your records ready
For every RCM entry, keep the supplier details, the invoice or self-invoice, proof of payment and the GSTR-3B reference. A tidy trail helps when you reconcile returns and when you answer queries. Make sure your own outward documents are also in order; our GST tax invoice checklist covers the mandatory fields.
Late payment of RCM tax carries interest, and a late return carries a fee. Our worked example on GSTR-3B late fee and interest shows how this is calculated. Before each filing, run through the GSTR-3B pre-filing checklist and add an RCM line to it.
The GSTR-3B due date is usually the 20th of the following month for monthly filers; check the GST portal for any extension.
Key takeaways
- Under RCM the recipient pays GST; only notified supplies qualify.
- Pay RCM tax in cash, then claim ITC if eligible.
- Issue a self-invoice when buying from an unregistered supplier on RCM.
- Check the current CBIC notifications and confirm specifics with your chartered accountant.
If you want one place to keep purchase records and reconcile them each month, you can explore AICOUNTLY Smart Books as part of your monthly routine.