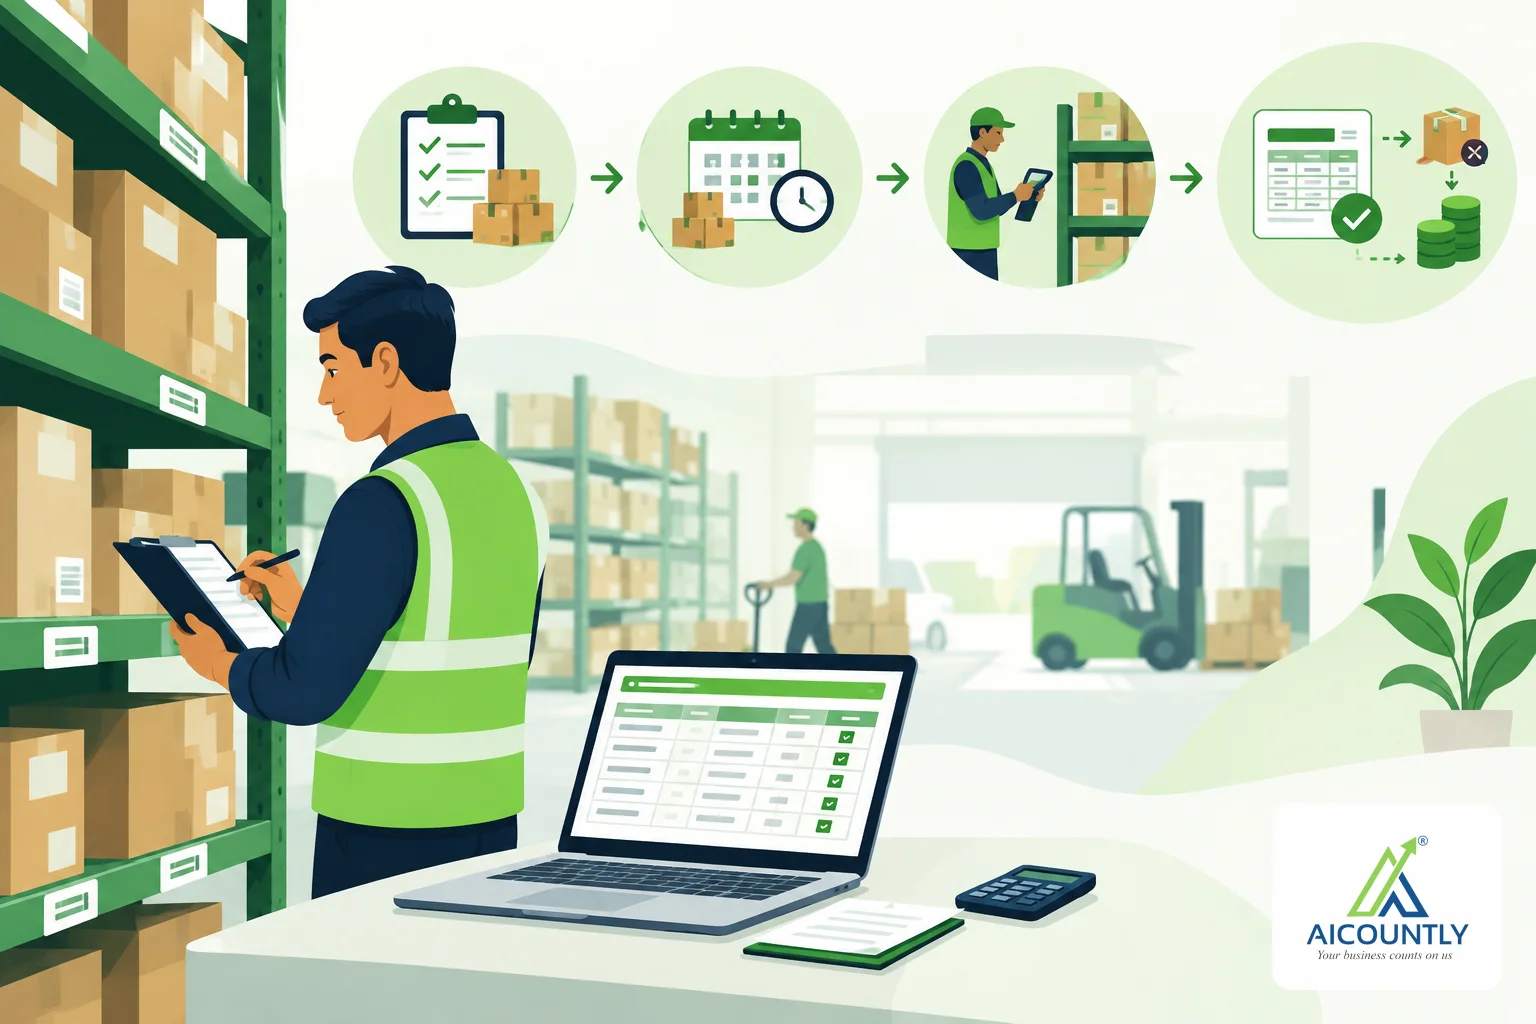
Physical stock verification means counting the goods actually lying in your shop, godown or factory and matching that count with what your books say. If you do it properly at least once or twice a year, you find shrinkage, wrong entries and slow-moving stock before they distort your profit and your GST position.
This guide gives a practical routine that a small trader, manufacturer or retailer can follow without special tools. It is general guidance; confirm specifics for your business with your chartered accountant.
Why physical stock verification matters
Closing stock is a direct input into your profit. If the books show more stock than you really hold, profit is overstated. If they show less, profit is understated. Either way, the numbers you use for tax, bank limits and decisions are wrong.
Stock records also matter under GST. Section 35(1) of the CGST Act requires a registered person to keep accounts that include the stock of goods, and the GST rules ask for stock registers for goods. A count that matches your records is the simplest evidence that you maintain them honestly.
Before the count: prepare
- Fix the date. Pick a count date, ideally a period-end such as 31 March or the close of a half-year. Our half-year book closing checklist shows where the count fits in a wider closing routine.
- Freeze movements. If you can, stop dispatches and receipts during the count. If you cannot, note every in and out movement with time and document number.
- Take a book snapshot. Print or export the book stock by item and location as on the count date, but do not hand it to counters. A blind count is more reliable.
- Cut off documents. Note the last purchase invoice, goods receipt, sales invoice and delivery challan number before and after the count. This is your cut-off.
- Assign teams. Use two people per area: one counts, the other records. Someone independent of the storekeeper should supervise.
During the count: a simple method
- Divide the premises into zones and tag each zone so nothing is counted twice or missed.
- Count item by item. Write the unit of measure, quantity, batch or lot where relevant, and condition (good, damaged, expired).
- Keep separate lists for goods held on behalf of others, goods sent out on job work or approval, and goods in transit. These need different treatment.
- Have a second person re-count high-value items and a random sample of the rest.
- Sign and date every count sheet. Do not erase; cross out and initial corrections.
Reconcile the count with the books
Now compare the counted quantity with the book quantity, item by item. Differences usually come from a handful of causes:
Cause of differenceWhat to check TimingPurchases received but invoice not yet booked, or sales invoiced but goods still in the godown Wrong unit or itemBoxes versus pieces, or two codes used for the same item Unrecorded issuesFree samples, internal use, replacements or returns not entered LossTheft, breakage, spoilage or evaporation Data entryQuantities typed wrongly in a purchase or saleFirst clear the timing and entry errors using your cut-off notes. Whatever remains is a genuine surplus or shortage that needs an adjustment entry, with the reason recorded and a person authorised to approve it.
Valuing the stock
Under Indian accounting standards, inventories are generally valued at the lower of cost and net realisable value. Net realisable value is the price you expect to get, less the cost of completing and selling the item. Damaged, expired or obsolete items may need to be written down. Use one consistent cost method, such as FIFO or weighted average, and apply it every year. Your CA will advise on the method suited to your business.
GST points when stock is lost or written off
If goods are lost, stolen, destroyed or written off, Section 17(5)(h) blocks input tax credit on them, which generally means credit already taken must be reversed. Our guides on blocked credit under Section 17(5) and ITC reversal explain how to think about reversals. Do not write off stock casually; record the reason and keep evidence such as a police complaint, insurance claim or disposal record.
Fix the process, not just the numbers
- Count fast-moving or high-value items more often through cycle counts, for example a few items every week.
- Give each item one code, one unit and one storage location.
- Enter purchases and sales on the same day the goods move.
- Review the same way you review cash: our monthly bank reconciliation routine works well alongside a monthly stock check.
- Track reasons for every adjustment so repeat problems show up.
Key takeaways
- Count blind, with documented cut-off, signed count sheets and independent supervision.
- Resolve timing and entry errors first; adjust only the genuine differences, with approval.
- Value stock at the lower of cost and net realisable value, using a consistent method.
- Lost or written-off goods can trigger an ITC reversal under Section 17(5)(h); keep evidence.
- Use regular cycle counts so the year-end count holds few surprises.
If you are looking for a tool to keep item-wise stock records in one place, you can read more about AICOUNTLY Inventory on its product page.