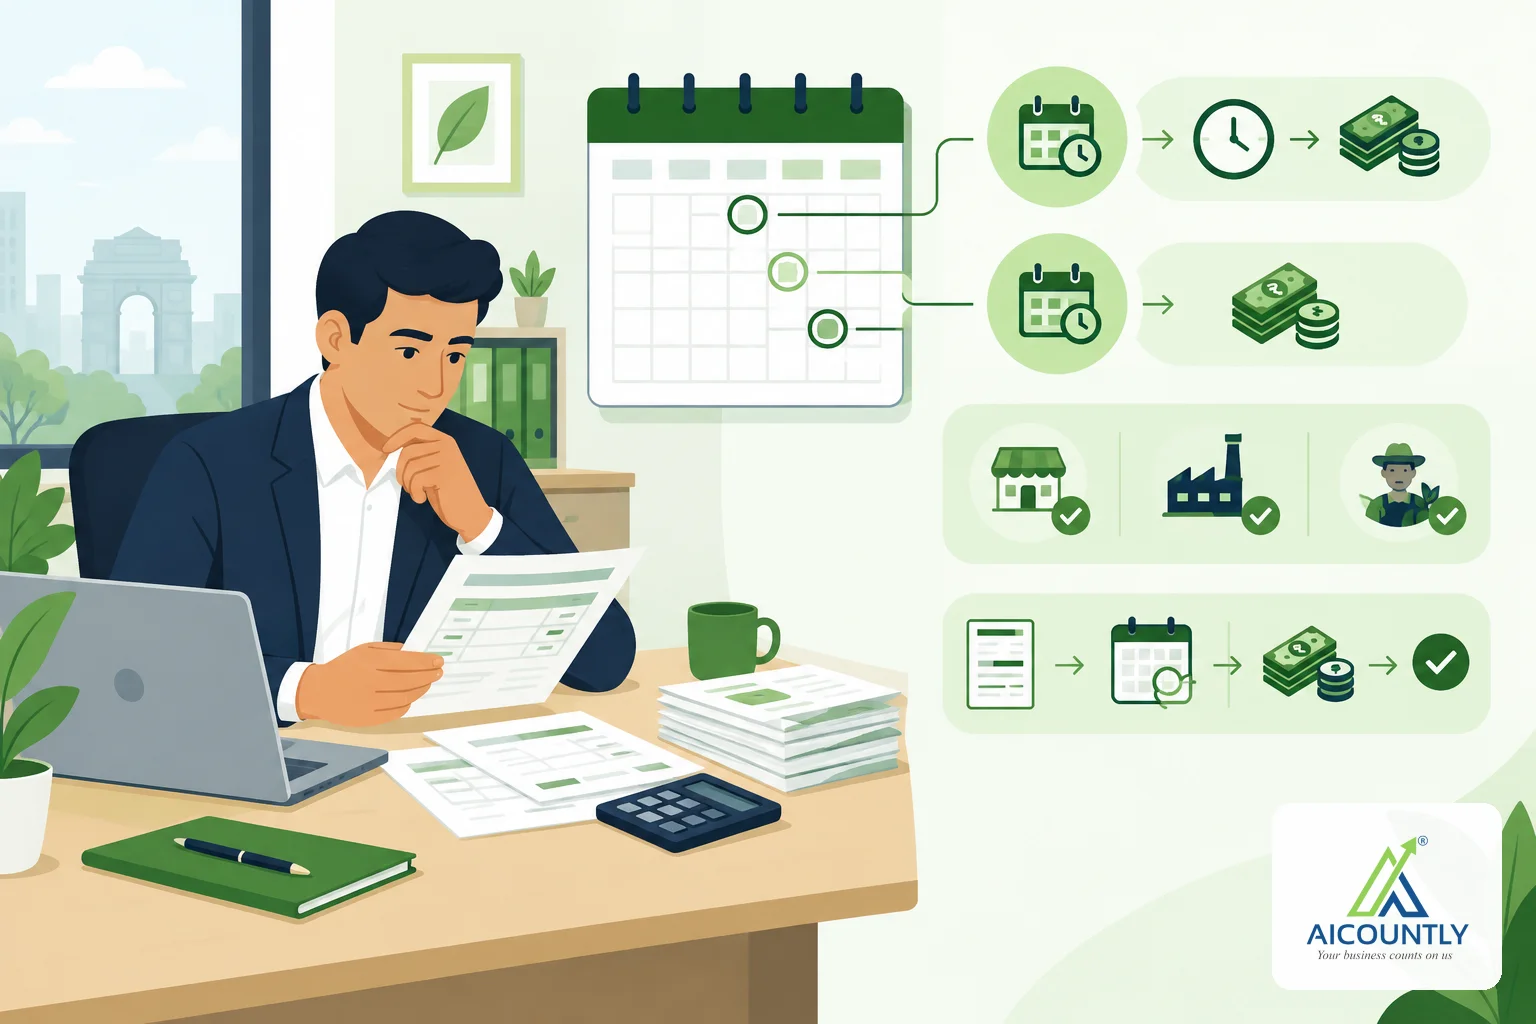
Section 43B(h) of the Income-tax Act, 1961 says you can claim a deduction for what you owe a micro or small enterprise supplier only when you actually pay it, if you pay later than the legal time limit. That time limit is 15 days, or up to 45 days if you have a written agreement. With the financial year ending on 31 March, October is a good time to check your supplier payments before the unpaid amounts turn into a tax cost.
What section 43B(h) does
Normally, a business on the mercantile (accrual) system claims an expense when it is incurred, even if the supplier has not yet been paid. Section 43B is an exception for certain items: they are allowed only on payment. Clause (h), added by the Finance Act, 2023, brought in amounts payable to micro and small enterprises for goods supplied or services rendered. It applies from assessment year 2024-25 onwards, that is, from financial year 2023-24.
In simple terms: if you buy from a registered micro or small supplier and you do not pay within the permitted period, that purchase cost is not deductible in the year you booked it. It becomes deductible in the year you actually pay.
The 15 and 45 day rule
The time limit comes from section 15 of the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006.
- No written agreement: payment must be made before the agreed date or, if there is none, within 15 days of the day of acceptance of the goods or services.
- Written agreement: the agreed period applies, but it cannot exceed 45 days from the day of acceptance (or deemed acceptance).
"Day of acceptance" is usually the date you receive the goods or the service is completed. If you object to the goods or services in writing within the period allowed by the MSMED Act, the "deemed acceptance" date can shift. Keep your goods receipt and objection records in order.
Who counts as a micro or small supplier
- The supplier must be registered under the MSMED Act, which in practice means holding an Udyam registration.
- Only micro and small enterprises are covered. Medium enterprises are not.
- The supplier's status on the date of supply is what matters, so ask suppliers for their Udyam certificate and keep a copy.
If a supplier is not registered, or you cannot confirm the registration, the clause does not apply to that supplier. Do not assume, though. Many small suppliers register without telling customers, so ask.
An example
SituationTime limitIf paid late Invoice accepted 10 September, no agreement15 days, so by 25 SeptemberNot deductible in FY 2026-27 if still unpaid at 31 March 2027; deductible in the year it is paid Invoice accepted 10 September, written agreement for 60 daysCapped at 45 days, so by 25 OctoberSame treatment: the 60-day term does not extend the limit Same invoice paid within the limitMetDeductible in the year bookedThe unusual point is that the usual relief under section 43B, where payment before the due date of your return still gets you the deduction in the year of accrual, does not help for clause (h). What matters is whether the payment was inside the MSMED time limit, so confirm the exact wording with your CA.
The interest risk is separate
Section 16 of the MSMED Act provides for compound interest on delayed payments to micro and small suppliers, at three times the bank rate notified by the Reserve Bank of India. That is a commercial liability, in addition to the tax effect. Interest paid is also generally not something you can assume to be deductible, so check with your CA.
What to do before year-end
- Tag your vendors. Mark which suppliers are micro or small, with their Udyam number, in your vendor master.
- Run an ageing report. List all unpaid invoices from tagged vendors by days since acceptance.
- Check your agreements. Make sure any credit period longer than 15 days is in a written agreement and does not exceed 45 days.
- Pay overdue amounts before 31 March where cash flow allows, so the cost is deductible in the current year.
- Reconcile your books. Matching what you owe against vendor statements avoids disputes about acceptance dates. See our guide to bookkeeping basics for growing businesses.
- Prepare for reporting. Companies that owe MSME suppliers beyond 45 days have separate reporting duties, including the half-yearly MSME-1 return. Check the current rules with your CA or company secretary.
- Prepare for the tax audit. The tax audit report (Form 3CD) asks for details of amounts inadmissible under section 43B(h), so your auditor will ask for this data. Related reading: a year-round income tax compliance checklist.
Common mistakes
- Assuming a 60 or 90 day credit term agreed over email or phone is valid. The cap is 45 days, and the agreement must be in writing.
- Treating all small vendors as covered. Only Udyam-registered micro and small enterprises count.
- Using the invoice date instead of the date of acceptance when counting days.
- Paying part of an invoice and assuming the full amount is protected. Check how the unpaid balance is treated.
- Ignoring the rule for services. It covers both goods and services.
Key takeaways
- Amounts owed to micro and small suppliers are deductible only when paid, if paid beyond the time limit.
- The limit is 15 days, or at most 45 days with a written agreement.
- Only Udyam-registered micro and small suppliers are covered, not medium ones.
- Review ageing of supplier dues well before 31 March.
- Interest under the MSMED Act is a separate cost for late payment.
An accounting tool such as Smart Books can help you keep vendor-wise payables and ageing in one place, but the key step is simple: know which suppliers are covered and pay them on time. This is general guidance, so confirm specifics with your chartered accountant.