GSTR-1 is the return where you report your outward supplies, and the mistakes people make in it usually travel into your customers' GSTR-2B and your own GSTR-3B. This guide shows how to file GSTR-1 without common mistakes, with a simple routine you can repeat every month or quarter.
If you are new to the full monthly cycle, read our GST filing checklist for small businesses alongside this article.
What GSTR-1 is and why accuracy matters
GSTR-1 is a statement of sales: invoices issued to registered buyers (B2B), invoices to unregistered buyers (B2C), exports, credit and debit notes, and amendments. It does not carry a tax payment by itself. The tax is paid through GSTR-3B.
What you report here flows to your buyers' GSTR-2A and GSTR-2B. A wrong GSTIN or a missing invoice means your customer may not see the input tax credit (ITC), and they will call you about it.
Know your due date and filing frequency
Monthly filers normally file GSTR-1 by the 11th of the following month. Businesses that opted for the QRMP scheme file GSTR-1 quarterly, normally by the 13th of the month after the quarter, and may upload B2B invoices earlier through the Invoice Furnishing Facility. These are the usual statutory dates; extensions are sometimes notified, so confirm on the GST portal before the date.
A late return attracts a daily late fee, and a nil return is charged at a lower rate. Check the current amounts on the GST portal or with your CA instead of relying on old figures.
Common mistakes and how to avoid them
1. Wrong or missing GSTIN of the buyer
A single wrong digit sends the invoice to the wrong person, or the portal rejects it. Verify the GSTIN of every new customer on the portal before you issue the first invoice, and keep it stored in your customer master.
2. Wrong place of supply
Place of supply decides whether you charge CGST plus SGST or IGST. Mistakes are common when goods are shipped to a different state from the billing address. Decide it from the rules for your supply, not from habit.
3. Wrong tax rate or tax type
Check the rate against the HSN or SAC of the item. Charging CGST plus SGST on an interstate sale, or IGST on an intrastate sale, shows up quickly in your buyer's credit.
4. HSN or SAC summary errors
GSTR-1 asks for an HSN-wise summary of outward supplies. The number of digits required depends on your turnover, so check the current rule for your business. Make sure the quantity, unit and values in the summary agree with your invoices.
5. Missing credit and debit notes
Credit notes reduce your liability and debit notes increase it. If a credit note is left out, you pay tax on a sale that was already reversed. Report them in the correct period and link them to the original invoice.
6. Duplicate or missed invoices
Invoices that are entered twice inflate your tax; invoices that are missed leave your customer without credit. Check that your invoice series is continuous and that every number is either reported or cancelled.
7. Mixing B2B and B2C
If a buyer has a GSTIN and the invoice was issued with it, it belongs in B2B. Putting it under B2C hides it from the buyer's records.
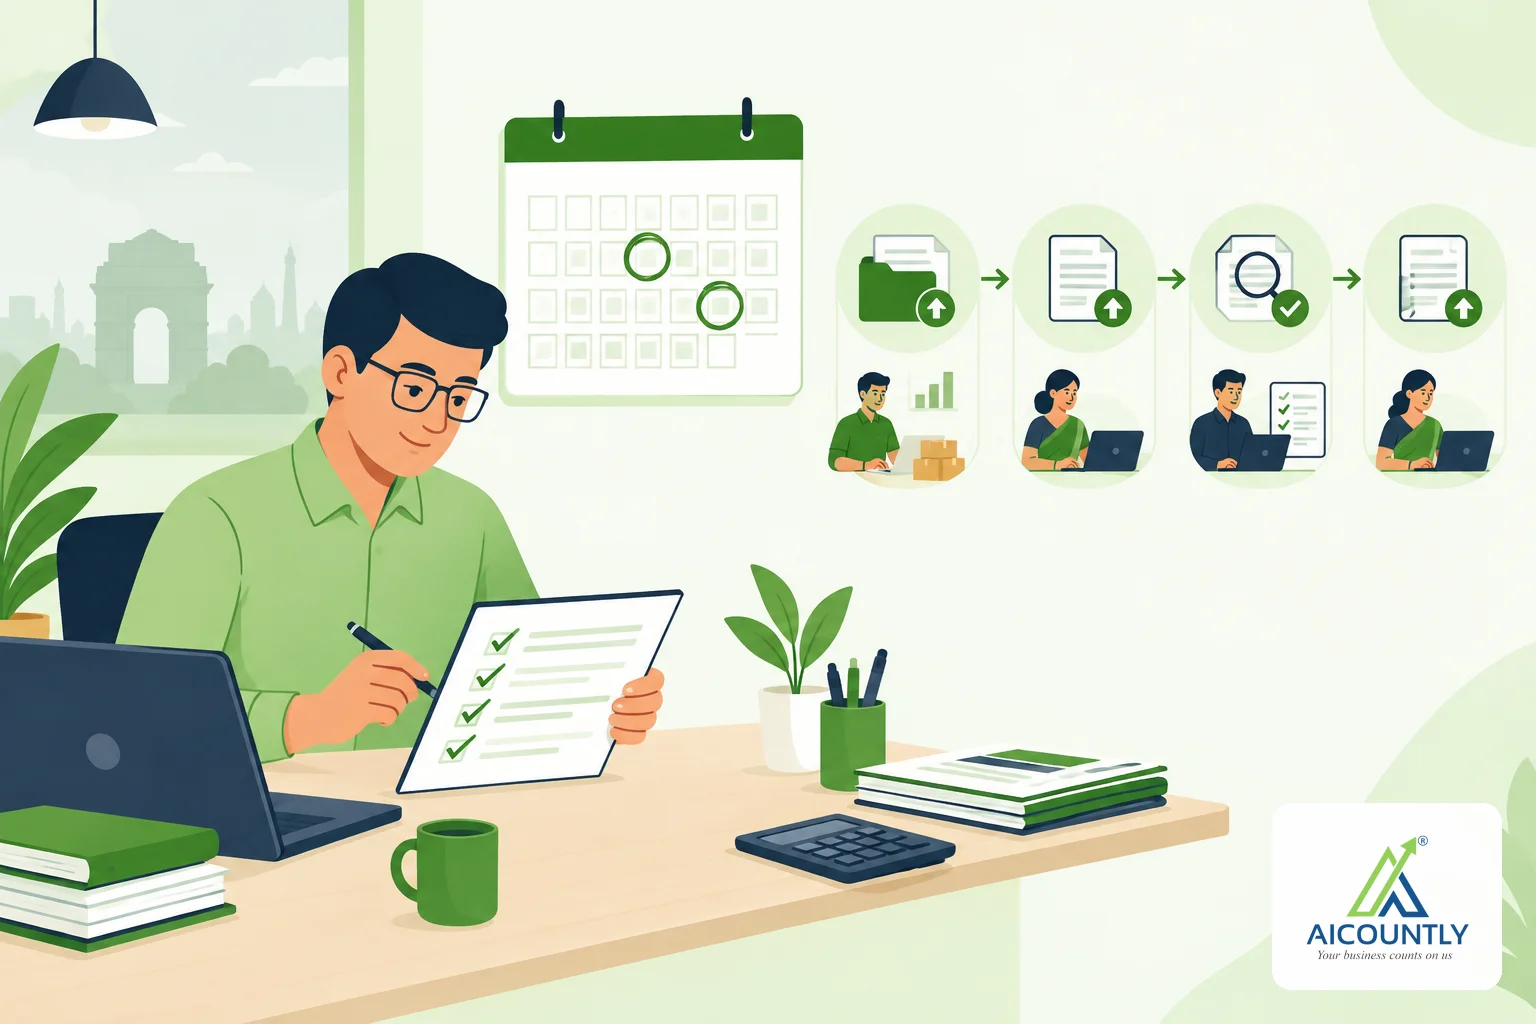
A step-by-step routine before you file
- Close the period. Make sure all invoices, credit notes and debit notes for the month or quarter are entered in your books.
- Tally with the books. Compare total taxable value and tax in your sales register with the totals in your GSTR-1 data.
- Review the invoices. Check the GSTIN, place of supply, rate and invoice number on each B2B entry.
- Check the summary. Review the HSN summary and the document summary of invoices issued and cancelled.
- Preview and file. Use the summary or preview on the portal, correct what looks wrong, then submit and file with your signature (DSC or EVC).
- Save the acknowledgement. Keep the ARN and the filed summary with your records.
What if you find an error after filing?
Once GSTR-1 is filed, you generally cannot edit it. Corrections are made through the amendment tables in a later GSTR-1, and for some details a separate amendment facility exists on the portal. Where the error changes tax, adjust it in GSTR-3B as the rules allow. Because the rules for amendments and time limits change, check the current position on the portal or ask your CA before correcting a large entry.
Also compare GSTR-1 with GSTR-3B every month. Our guide on GSTR-1 vs GSTR-3B reconciliation shows how to find mismatches. If you issue e-invoices, also read e-invoicing under GST, because IRN-reported invoices are the basis of the data that appears in your return.
Habits that keep your return clean
- Issue every invoice from one system with a continuous series.
- Keep an up-to-date customer master with verified GSTINs.
- Do not wait until the last day; start reviewing a week before the due date.
- Record credit notes on the same day they are issued.
- Keep a short monthly checklist and sign it off.
Key takeaways
- GSTR-1 reports your sales and feeds your buyers' ITC, so errors affect them too.
- Monthly filers normally file by the 11th; QRMP filers by the 13th after the quarter. Confirm any extension on the portal.
- The most common mistakes are wrong GSTIN, place of supply, tax rate, HSN summary and missed credit notes.
- Tally GSTR-1 with your sales register before you file.
- After filing, fix errors through amendments and always confirm specifics with your CA.
If you want your invoices, customers and GST details in one place, Aicountly's Billing app is built for creating GST invoices; this guide is general information and not professional advice, so check the details with a chartered accountant.