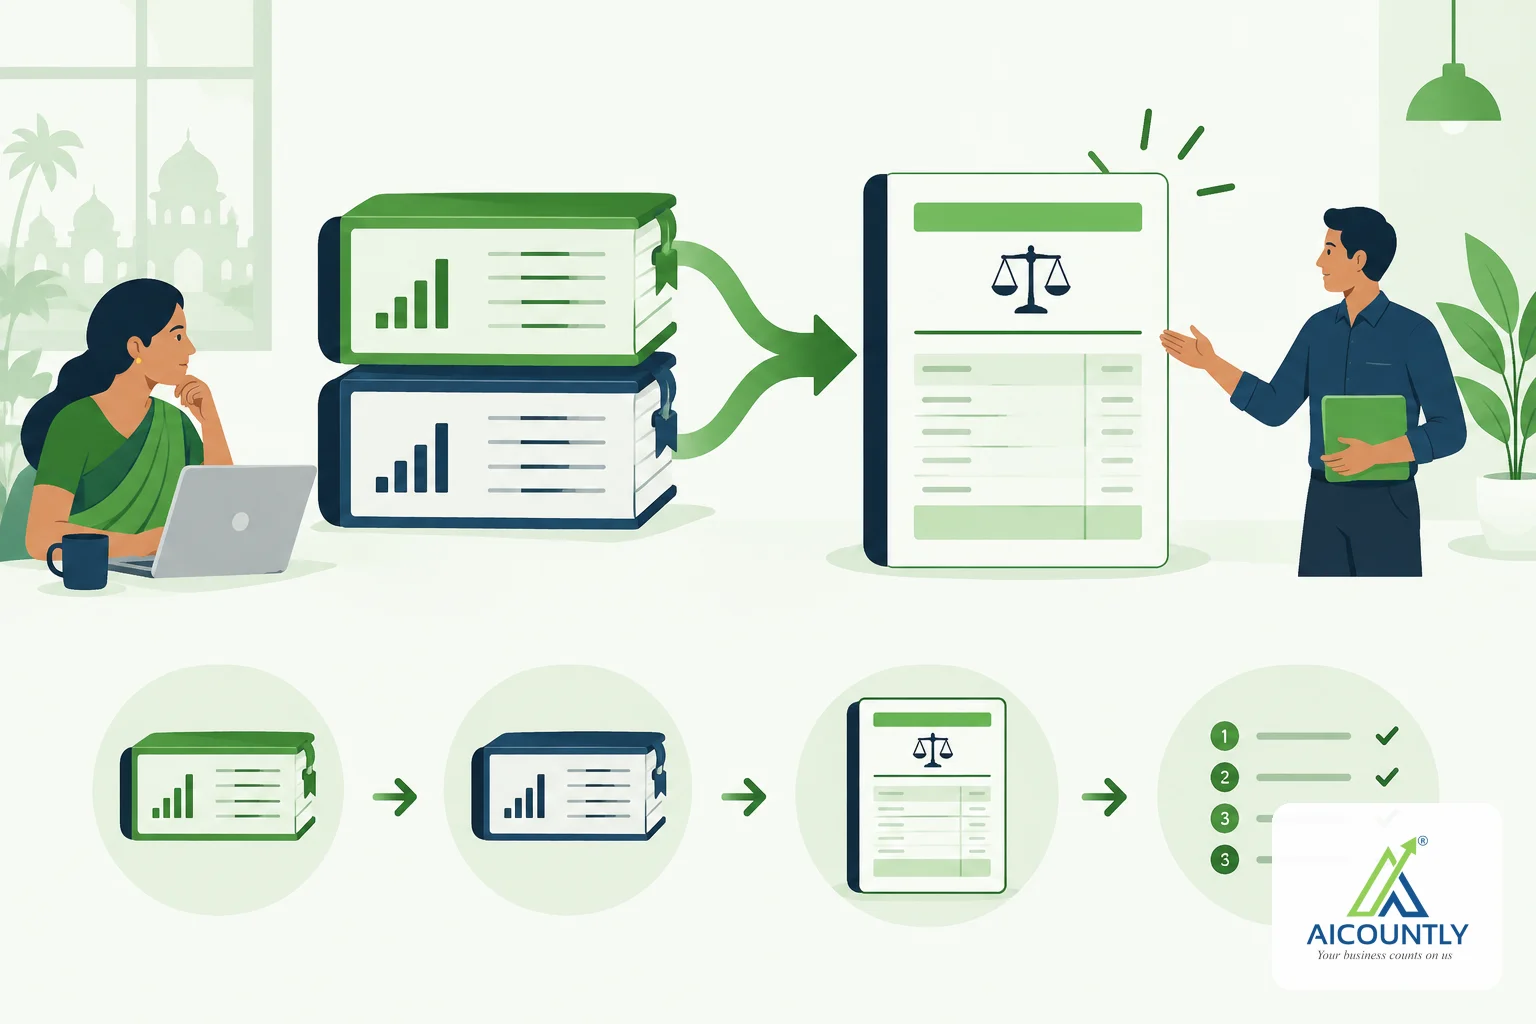
The Profit & Loss Account on your Balance Sheet often differs from the net profit or loss on your P&L report because the two answer different questions. The Balance Sheet line is the profit brought forward from earlier periods plus this year's result; the P&L report shows this year alone. If the two figures look like a mismatch, it is usually a presentation gap, not an error in your books.
What each statement is actually telling you
The Profit & Loss report covers a period, normally one financial year. It adds up income and expenses for that period only and ends with a net profit or net loss. Nothing from earlier years is in it.
The Balance Sheet is a position on one date. Its "Profit & Loss Account" line sits on the liabilities side as part of owners' funds, and it has to carry everything that has not yet been moved to capital or reserves. That includes the result of the current year and any balance brought forward from before.
So the Balance Sheet line is, in simple terms:
Balance brought forward + current period result = Profit & Loss Account on the Balance Sheet
A worked example (illustrative numbers)
Suppose a trading business closed its earlier years with a cumulative profit of ₹12,00,000 that was never transferred to a capital or reserve account. In the current year it earns a net profit of ₹8,00,000.
ItemAmount (₹) Profit brought forward (opening)12,00,000 Current year result (as on the P&L report)8,00,000 Profit & Loss Account on the Balance Sheet20,00,000The P&L report says ₹8,00,000 and the Balance Sheet says ₹20,00,000. Both are right. The gap of ₹12,00,000 is exactly the opening balance. The same logic works with losses: a brought-forward loss makes the Balance Sheet figure look worse than the year's own loss.
Why the gap shows up in some books and not others
If you started the company in the software this year, or if your income and expense ledgers closed neatly to zero at each year end, there is nothing brought forward. The line then equals the P&L result and the two statements agree at first glance.
The gap appears when income and expense ledgers carry opening balances into the financial year. This is common after migrating from another accounting package, when openings are keyed in for every ledger, or when a prior year's profit was left sitting in the P&L ledgers instead of being transferred.
How to reconcile the two figures in four steps
- Note the Balance Sheet line. Write down the Profit & Loss Account figure and its "as on" date.
- Note the P&L report result for the same financial year, with the same branch or scope selected. A different date range or branch filter is the other common cause of a difference.
- Subtract. The difference should equal the opening balances sitting in your income and expense ledgers. List those ledgers and add their openings.
- Decide whether the openings are right. If they are genuine retained profit or loss, nothing needs fixing, though your CA may want it transferred to reserves or capital under your accounting policy. If they are stray amounts from a migration, correct them with a proper opening entry.
Your auditor will ask for exactly this bridge. The statements in Schedule III format present reserves and surplus as one head, so a clear split between "brought forward" and "for the year" helps in the notes too.
How Smart Books shows the split
In the Smart Books code, when income or expense ledgers hold financial-year openings, the Balance Sheet's Profit & Loss Account line now carries two child lines instead of one undivided figure:
- Opening Balance (brought forward): lists the income and expense ledgers that hold those openings, each with its amount, so you can see which ledgers they are.
- Current Period: the year's own result, the same figure the Profit & Loss report states.
The total of the line, the totals of the Balance Sheet and the printed statement do not change; only the presentation does. The Balance Sheet data also returns the opening, current and total values for the line, so the three numbers always add up to the paisa.
Common mistakes to avoid
- "Fixing" a correct figure. Do not post adjusting entries just to make the Balance Sheet match the P&L report. The two are meant to differ by the brought-forward balance.
- Comparing different scopes. Check that both reports use the same financial year, date and branch.
- Leaving openings unexplained. A large brought-forward balance with no note invites audit questions. Keep a one-line explanation in your year-end file.
- Ignoring stock. Closing stock affects the year's result, so confirm stock is valued before you compare. Our guide to reconciling physical stock with your books helps here.
Key takeaways
- The P&L report shows one period; the Balance Sheet line shows brought-forward balance plus that period.
- A difference equal to the opening balances in income and expense ledgers is normal, not an error.
- Always compare the same financial year, date and branch before concluding anything is wrong.
- Keep a short note on what the brought-forward amount is, for your CA and auditor.
If you keep your books in Smart Books, the Balance Sheet now shows the opening and current-period parts of the Profit & Loss Account side by side, which saves the manual bridge. For a wider year-end routine, see our half-year book closing checklist, and confirm treatment of retained profit with your chartered accountant.