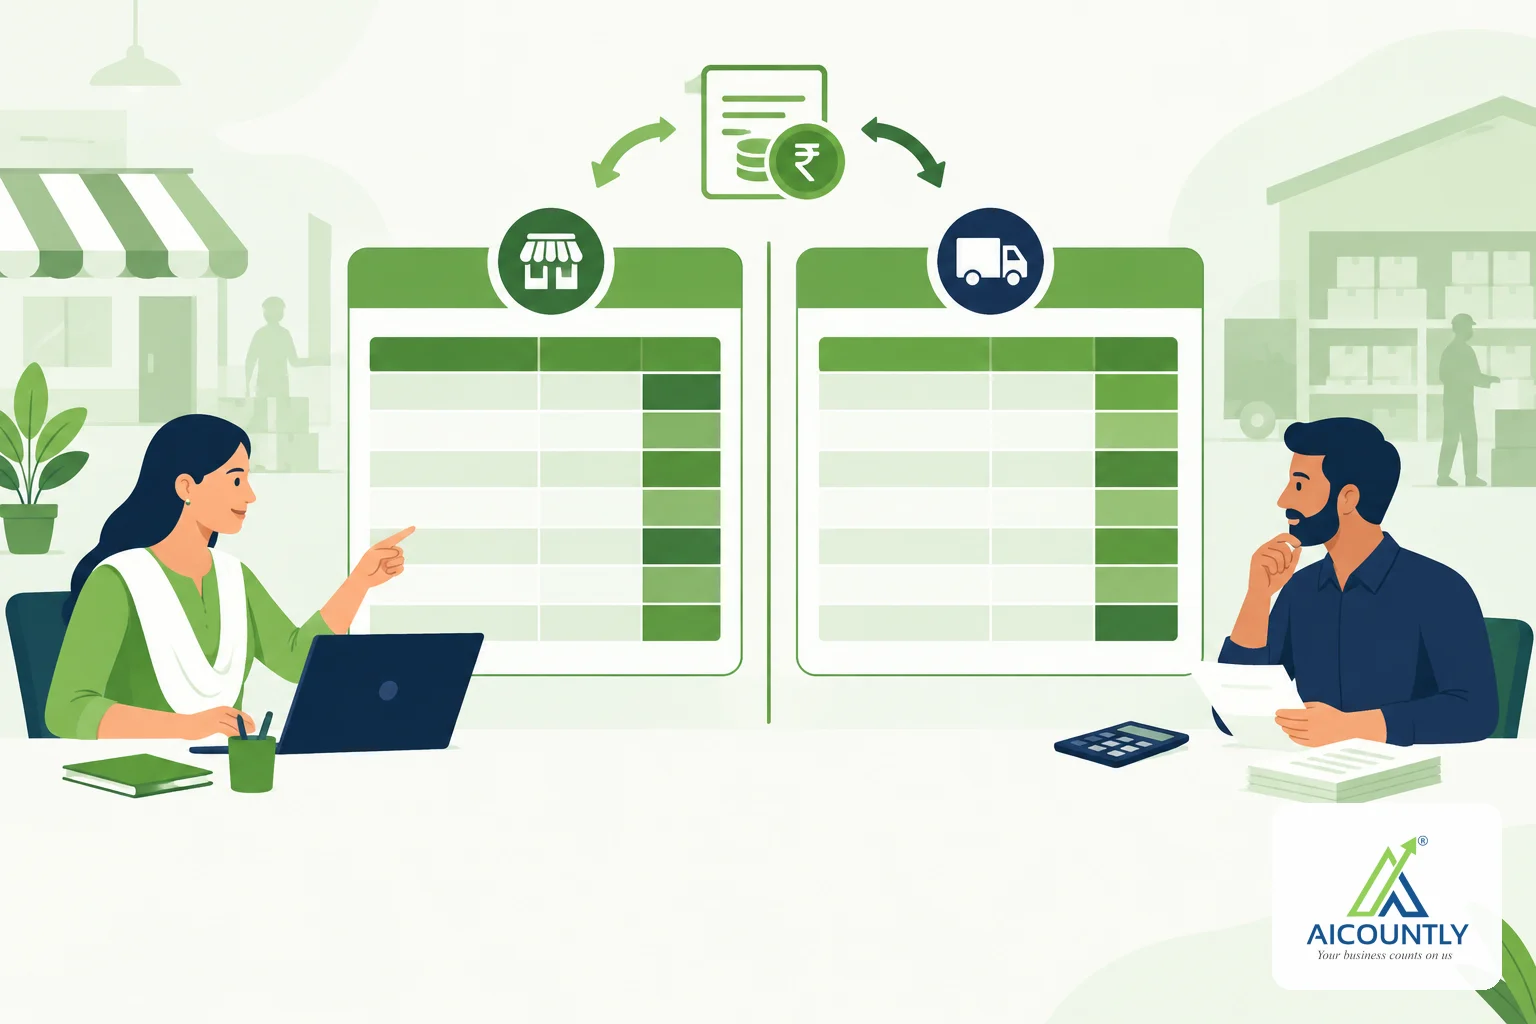
A GST rate-wise summary should show sales and purchases as two separate blocks, never as one combined figure. The tax you charged customers and the tax you paid suppliers are different numbers with different purposes, and a single "18% row" that adds them tells you nothing you can file or pay.
If you have ever looked at a rate-wise summary and wondered why the 18% tax figure matches neither your GSTR-1 nor your input tax credit, this article explains why, and how to read the report correctly.
What a GST rate-wise summary is meant to show
A rate-wise summary groups your vouchers by GST rate: 0%, 5%, 12%, 18%, 28% and so on. For each rate it totals the taxable value and the tax split into IGST, CGST and SGST. It is a quick sanity check before you file: does the tax you are about to report at each rate look reasonable for the turnover at that rate?
That check only works if every row means one thing. A row that mixes two meanings cannot be checked against anything.
Why mixing sales and purchases gives a figure nobody files
Suppose in a month you sold goods worth Rs 10,000 plus 18% GST and bought goods worth Rs 8,000 plus 18% GST. Put both into one 18% row and you get Rs 18,000 taxable and Rs 3,240 of tax. But look at where each figure goes:
- Sales (outward supplies) feed your GSTR-1 and your output tax liability in GSTR-3B.
- Purchases (inward supplies) feed your input tax credit, which you match against GSTR-2B.
No return asks for "sales plus purchases at 18%". The combined taxable value is not your turnover, and the combined tax is neither a liability nor a credit. If you are using that number to cross-check a return, the check will always look wrong.
How credit and debit notes change a rate
Notes are where hand-built summaries usually go astray. A credit note you issue to a customer reduces your outward supply. A debit note you receive from a supplier, or a credit note you receive, adjusts your inward supply. In both cases the note sits at the same rate as the original supply.
For example, a sale of Rs 10,000 at 18% followed by a credit note of Rs 2,000 leaves Rs 8,000 taxable at 18% on the sales side, with CGST and SGST of Rs 720 each. If the note is stored with negative amounts and a tool works out the rate from those signed figures, the note can end up in a strange 0% row of its own instead of netting against the 18% row. Reading the rate from the unsigned amounts avoids that.
How Smart Books shows the two blocks
In Smart Books, open the GST area, choose Summaries and then Rate-wise. The report is split into two blocks, labelled Outward supplies (sales) and Inward supplies (purchases). Each block lists its rates with taxable value, IGST, CGST and SGST, and has its own totals line. The same totals lines carry into the CSV, Excel and PDF exports. There is no combined summary that adds the two blocks together.
Credit and debit notes are netted into the rate of the supply they adjust, so the 18% row on the sales side already reflects the credit note in the example above.
Drill into the vouchers behind each row
A summary is only useful if you can trace a number to its source. Each block in the Smart Books rate-wise report drills to its own register: a row in the sales block opens the outward vouchers at that rate, and a row in the purchases block opens the inward vouchers. Drill into the 18% sales row and you see the sale and the credit note that make up the figure.
If a total looks off, this is the quickest way to find the voucher responsible, whether it is a wrong rate on a line, a note posted against the wrong period or a purchase booked as a sale.
A short routine before you file
- Pick the same period you are about to file for.
- Open the sales block and compare each rate's taxable value and tax with your GSTR-1 summary.
- Open the purchases block and compare it with your inward registers and GSTR-2B reconciliation, not with your sales.
- Drill into any rate that looks unusual, especially a rate you do not normally sell or buy at.
- Check that credit and debit notes appear inside the rate of the original supply.
For the filing calendar around this check, see our GST November checklist for GSTR-1 and GSTR-3B. If you want to understand why one report's profit figure can differ from another report's, our article on the Balance Sheet's Profit & Loss Account versus your P&L report covers a similar "same word, different meaning" trap.
Key takeaways
- Sales tax and purchase tax answer different questions, so a rate-wise summary should keep them in separate blocks.
- A combined 18% figure is not your turnover, your liability or your credit.
- Credit and debit notes belong to the rate of the supply they adjust.
- Always be able to drill from a rate row to the vouchers behind it.
- Confirm specifics for your own case with your chartered accountant.
If you keep your books in Smart Books, the Rate-wise summary under GST Summaries gives you the outward and inward blocks, each with its own totals, so you can compare each one with the right return before you file.